
Does Home Insurance Cover Pipe Breaks in Spain?
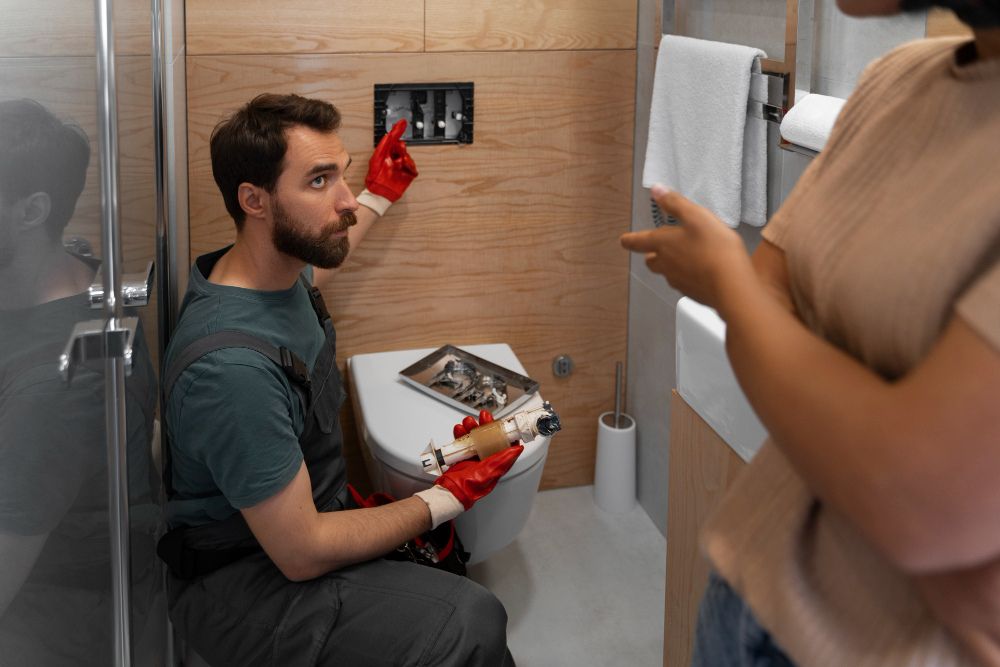
Burst pipes and water damage are common causes of home insurance claims in Spain. However, not all policies cover pipe repairs, hidden leak detection or damage caused to third parties in the same way.
A policy may cover the damage caused by escaping water without necessarily covering the repair of the pipe that caused the problem. Other policies may also include trace and access, opening walls or floors, and subsequent restoration work.
Exclusions may also apply where damage is related to corrosion, wear and tear, lack of maintenance or a leak that has developed gradually.
Understanding exactly what your policy covers before a problem occurs can help avoid unexpected costs when making a claim.
For a complete overview of how buildings, contents and liability cover work together:
Table of Contents
- Does Home Insurance Cover Pipe Breakage & Burst Pipes in Spain?
- What Water Damage May be Covered by Home Insurance in Spain
- What Happens If a Leak Damages Your Neighbour’s Property?
- What Water Damage May Be Excluded
- Trace & Access: Locating Hidden Leaks
- Common Water Damage Incidents in Spain
- How to File a Water Damage Claim in Spain
- Pipe Breaks in Rented Properties
- When Water Damage Cover Is Not Enough
- What Cover Should You Compare?
- Related Home Insurance Guides
- FAQs — Pipe Breaks & Water Damage Insurance in Spain
- Get Home Insurance in Spain with Appropriate Protection against Pipe Breaks
Does Home Insurance Cover Pipe Breaks in Spain?
Many home insurance policies can cover certain damage resulting from an accidental burst pipe or sudden escape of water.
Depending on the insurer and policy, cover may include:
- Accidental burst pipes
- Sudden water leaks
- Escape of water from internal installations
- Damage to walls, ceilings and floors
- Damage to fixed elements of the property
- Damage to insured belongings where contents cover applies
- Damage caused to third parties through liability cover
However, you should not assume that all of these protections are automatically included.
The policy may apply specific conditions to:
- Repairing the damaged pipe itself
- Locating hidden leaks
- Opening walls, ceilings or floors
- Reinstatement after access work
- Matching or aesthetic damage
- The age and condition of the plumbing installations
This is why the wording and limits of each policy should be reviewed carefully.
Water damage coverage depends on how your policy is structured. See:
Need Better Protection Against Water Damage?
Not all home insurance policies provide the same level of protection for burst pipes, hidden leaks, trace and access costs or damage caused to neighbouring properties.
If you own a property in Spain, we can help you compare cover options for expats, non-resident property owners and international residents.
What Water Damage May be Covered by Home Insurance in Spain
The cover available depends on the cause of the incident and the guarantees included in the policy.
1. Sudden Pipe Bursts
When a pipe breaks suddenly and unexpectedly, the policy may cover the resulting water damage.
Depending on the contract, it may also include:
- Access to the affected pipe
- Repair or replacement of the damaged section
- Drying affected areas
- Reinstatement of walls, ceilings or floors
It is important to distinguish between two separate concepts:
Resulting water damage: damage caused by the escaping water.
Pipe repair: repairing the component that caused the leak.
A policy covering the first does not necessarily mean that it also covers the second.
2. Leaks from Kitchens and Bathrooms
Accidental leaks from internal installations may be covered when their cause is sudden and falls within the policy guarantees.
Examples can include:
- Bathroom and kitchen plumbing
- Water supply installations
- Heating systems
- Other internal pipes
3. Damage to Insured Belongings
Where contents insurance is included, water damage to furniture, electronics and other insured belongings may be covered within the policy limits.
To understand the difference between the property itself and your belongings:
What Happens If a Leak Damages Your Neighbour’s Property?
This is particularly important in apartment buildings.
A leak originating from one property can cause damage to a neighbour’s:
- Ceilings
- Walls
- Floors
- Installations
- Furniture and other belongings
If the insured person is legally responsible for the damage and the incident falls within the policy terms, public or private liability cover may respond.
Depending on the policy, this may include:
- Damage caused to third-party property
- Compensation where legally due
- Legal defence connected with the claim
A leak does not automatically mean that the owner of the property where the water appeared is legally responsible.
The origin of the leak and the party responsible must first be established.
In apartment buildings, it may also be necessary to consider the community insurance policy where shared pipes or common elements are involved.
What Water Damage May Be Excluded
Home insurance is primarily intended to respond to insured accidental events rather than replace the normal maintenance of a property.
Exclusions vary between insurers, but several areas deserve particular attention.
Lack of Maintenance
Damage related to inadequate maintenance may be partially or completely excluded.
Examples can include:
- Advanced corrosion
- Wear and tear
- Deteriorated installations
- Known defects that have not been repaired
Slow or Gradual Leaks
A leak developing slowly over several weeks or months may be treated differently from a sudden and accidental pipe break.
Long-term damp and gradual deterioration can therefore create coverage issues.
Exterior Installations
Pipes located in gardens, terraces, swimming pools or other external areas may have different conditions or limits.
Defective Installations
Where the problem results from incorrect installation, defective construction or poor previous repair work, cover may be limited or excluded.
The general and specific conditions of the policy should always be checked to determine the actual scope of cover.
5. Construction Defects
If the issue is due to faulty construction, it may fall under the builder’s warranty instead of insurance.
In Spain, insurance activity and insurance distribution are subject to the Spanish regulatory framework and supervision by the Dirección General de Seguros y Fondos de Pensiones (DGSFP).
Trace & Access: Locating Hidden Leaks
An important area of water damage insurance is trace and access.
When the source of a leak is hidden behind a wall, beneath a floor or in another inaccessible area, work may be required simply to locate the problem.
Depending on the policy, trace and access cover may include:
- Locating the source of the leak
- Specialist leak detection equipment
- Thermal imaging or other detection methods
- Opening walls or ceilings
- Lifting sections of flooring
- Accessing the affected pipe
It is also important to check what happens after the leak has been located.
A policy may cover the cost of finding the leak while applying separate limits to Repairing the pipe, Closing the opened wall or floor, Restoring finishes, Matching tiles, flooring or paint.
For this reason, checking that a policy simply contains “water damage cover” is not enough.
If you are renting your home:
Does Your Policy Include Trace & Access?
We can help compare home insurance policies that include protection for water damage, hidden leak detection and liability.
Common Water Damage Incidents in Spain
Incidents that can lead to a water damage claim include:
- Burst pipes inside walls
- Leaks from bathrooms and kitchens
- Damage affecting neighbouring properties
- Electrical damage caused by water
- Damp resulting from a leak
- Hidden leaks requiring trace and access
Whether an incident is covered will depend on its cause and the terms of the individual policy.
How to File a Water Damage Claim in Spain
Taking appropriate action from the beginning can help limit further damage and make the claims process easier.
- Stop the Water, where possible and safe, close the main water supply or take reasonable measures to prevent further damage.
- Document the Damage, taking photographs or videos showing the leak, affected areas, damaged belongings, damage caused to neighbouring properties, where relevant.
- Notify the Insurer. Contact your insurer or broker as soon as reasonably possible.
- Keep Invoices and Receipts. Retain documentation for emergency repairs or measures taken to prevent further damage.
- Avoid Permanent Repairs Without Coordination, except for urgent work necessary to prevent additional damage.
- Cooperate with the Loss Adjuster.
Pipe Breaks in Rented Properties
Where a property is rented, different insurance policies may become relevant depending on the cause of the incident, who is responsible and what has been damaged.
If You Own the Property
The owner’s home insurance may include protection for:
- Buildings
- Private installations
- Water damage
- Property owner liability
- Landlord-owned contents where insured
The exact cover will depend on the policy.
If You Are a Tenant
The landlord’s insurance should not automatically be considered insurance for the tenant.
A dedicated renters insurance policy can protect:
- Personal belongings
- Tenant-owned furniture and equipment
- Tenant liability
- Certain accidental damage caused to third parties
- Other guarantees associated with living in a rented property
If a leak affects another property, the origin and responsibility must be established before determining which insurance policy should respond.
When Water Damage Cover Is Not Enough
Two home insurance policies can both include “water damage” while providing very different levels of protection.
A policy may cover the resulting water damage while limiting or excluding:
- Repair of the pipe itself
- Trace and access
- Opening and closing walls or floors
- Reinstatement of finishes
- Matching or aesthetic damage
- Certain external pipes
- Damage resulting from gradual deterioration
This is why home insurance should be compared by looking at the actual guarantees and limits rather than simply checking whether “water damage” appears on the policy.
Avoid Surprises When a Leak Occurs
Not all policies provide the same protection against burst pipes, hidden leaks or third-party damage.
We can help you compare options according to the characteristics of your property and the level of protection you need.
What Cover Should You Compare?
Rather than relying on labels such as Basic, Standard or Premium, it is more useful to compare the actual guarantees included in each policy.
| Coverage | What to Check |
|---|---|
| Water damage | Which causes are covered and what limits apply |
| Pipe repairs | Whether the damaged pipe itself is covered and under what circumstances |
| Trace & access | Whether locating and accessing a hidden leak is included |
| Reinstatement | Whether opened walls, ceilings or floors are restored |
| Matching / aesthetic damage | Available limit and conditions for matching finishes |
| Liability | Insured limit and third-party damage covered |
| Contents | Protection for furniture and belongings affected by water |
| Unoccupied property | Conditions or limits when the property is left vacant |
| Exterior installations | Conditions applying to terraces, gardens, pools or exterior pipes |
| Home assistance | Availability of emergency plumbing and related services |
A more comprehensive policy is not necessarily the one with the longest list of guarantees. It is the one that provides appropriate protection for the characteristics and use of the property.
For a complete explanation of how buildings, contents and liability cover work together:
Related Home Insurance Guides
FAQs — Pipe Breaks & Water Damage Insurance in Spain
1.Why do some insurers in Spain cover water damage but not the pipe repair itself?
Some home insurance policies in Spain separate the resulting water damage from the original cause of the leak. Insurers may pay for damaged walls, floors or ceilings while excluding the repair or replacement of old, corroded or poorly maintained pipes.
2.What is “trace & access” cover in Spanish home insurance?
Trace & access cover in home insurance Spain policies pays for locating hidden leaks behind walls, ceilings or floors. This may include opening structural elements, leak detection technology and access work needed before repairs can begin.
3.Who pays if a water leak from my property damages my neighbour?
It depends on the cause of the leak and who is legally responsible. Where the insured is responsible and the incident is covered, liability insurance may respond. If the source is a community installation or another party is responsible, a different policy may need to intervene.
4.Why can slow leaks and damp create insurance coverage problems?
Because many policies distinguish between sudden accidental damage and deterioration developing gradually over time. Long-term damp, corrosion, wear and tear and lack of maintenance may be subject to exclusions.
5.Does home insurance cover old or corroded pipes?
It depends on the policy and the cause of the damage. Old pipes are not necessarily excluded simply because of their age, but damage caused by corrosion, progressive deterioration, inadequate maintenance or known defects may be excluded.
6.What happens if a pipe bursts while the property is unoccupied?
Cover depends on the conditions of the policy, how long the property has been unoccupied, any prevention requirements imposed by the insurer and whether the property's actual use was correctly declared. This is particularly relevant for holiday homes and second residences.
7.Are hidden leaks inside walls or floors covered?
They can be, but trace and access should be checked specifically. A policy may cover resulting water damage without necessarily covering all the costs of locating and accessing the source of the leak.
8.What is the difference between a water leak and water ingress?
A leak generally involves water escaping from a pipe or installation. Water ingress may come from roofs, façades, terraces, external areas or waterproofing defects. The source matters because different policy guarantees may apply.
9.Do tenants need protection against water damage?
They may do. A landlord's insurance does not necessarily protect the tenant's belongings or personal liability. Renters insurance can include contents protection and liability for certain accidental damage caused to third parties.
10.What is a common mistake when choosing water damage cover?
Assuming that the words “water damage” automatically mean that pipe repair, trace and access, opening and reinstatement work, aesthetic damage and liability are all included. These guarantees should be checked individually.
11.What cover should I check for protection against burst pipes?
It is worth checking water damage, pipe repair, trace and access, reinstatement, liability, contents protection, emergency assistance and, where relevant, matching or aesthetic damage.
12.Why is water damage particularly important in apartment buildings?
Because a leak can affect not only the property where it originates but also neighbouring apartments and common areas. Depending on the cause, the individual home policy, liability cover and the community insurance policy may all become relevant.
Get home insurance in Spain with appropriate protection against pipe breaks.
Avoid discovering the limitations of your policy after a leak occurs.
We can help you compare home insurance taking into account water damage, pipe repairs, trace and access, liability and protection for the property.
- Fast · Clear · No pressure · Support in English and Spanish